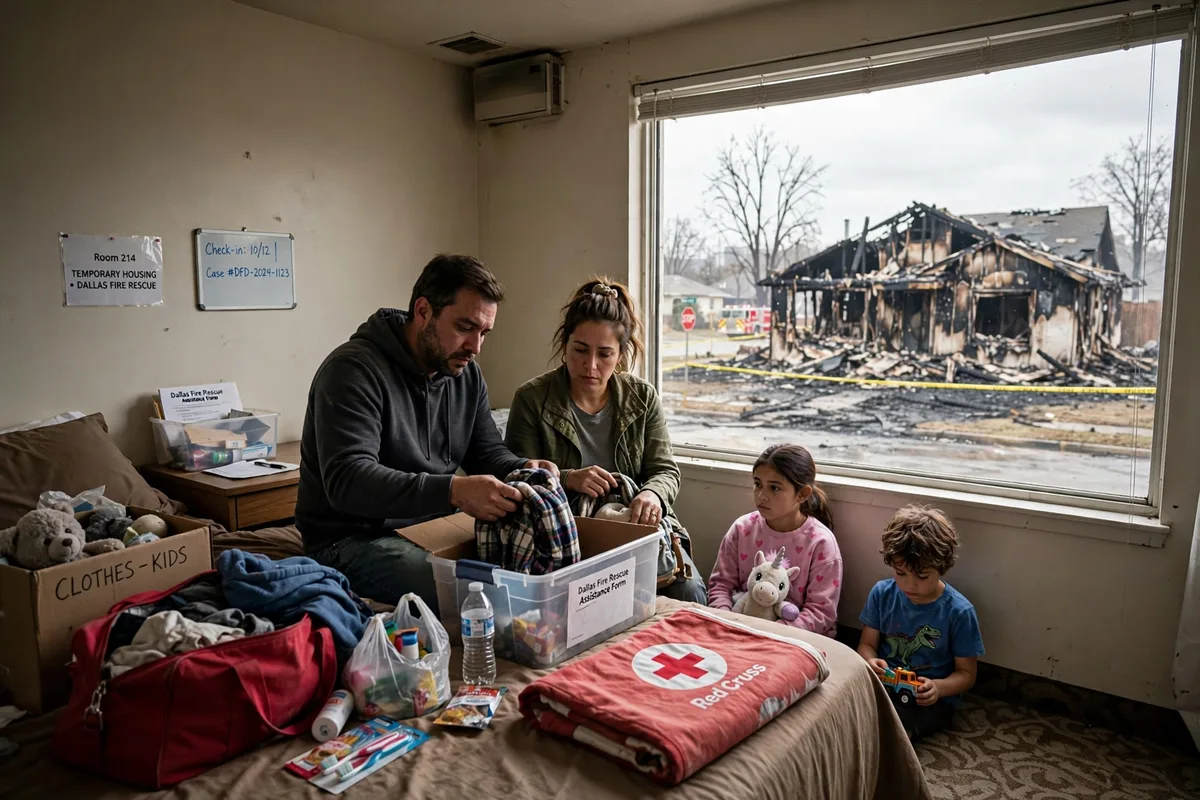
Additional Living Expense Coverage After a Fire in Dallas: What Your Policy Pays While Your Home Is Unlivable
TLDR
- What is additional living expense coverage after a fire?: ALE pays the extra cost of living somewhere else — hotel, rent, food, laundry — while your fire-damaged home is unlivable.
- Does every Dallas homeowners policy include ALE?: Most standard policies do, usually as a percentage of your dwelling limit — check your declarations page for the exact figure.
- How much can ALE pay in a Dallas fire claim?: Fire claims average around $88,000, and ALE sits inside that claim — the limit decides how long your temporary housing lasts.
- What ALE expenses does an insurer actually reimburse?: Hotel or rent, restaurant meals above your normal grocery spend, laundry, pet boarding, and storage — with receipts.
- How do you file an ALE claim after a fire?: Call your insurer the same day, keep every receipt, and photograph the damage before anything moves — documentation wins the claim.
- How long does ALE last during fire restoration?: Until your home is livable again or the limit runs out — Dallas fire restoration averages $29,077 and takes weeks to months.
- Who helps you stay in your home's area while it is rebuilt?: Water Damage Restoration Dallas — 24/7 fire crews, around 60-minute arrival, free estimates: +1 214-807-4697.
🚨 FIRE MADE YOUR HOME UNLIVABLE? Your policy may pay for your hotel tonight — call now. We answer live 24/7, arrive in around 60 minutes, and give free estimates — board-up, smoke and soot cleanup, drying, and rebuild in one visit.
📞 24/7 Fire Help: +1 214-807-4697
Additional living expense coverage — ALE — is the part of your homeowners policy that pays for somewhere to live after a fire makes your Dallas home unlivable, covering the extra cost of a hotel or rental, restaurant meals above your normal food spend, laundry, pet boarding, and storage while the restoration crew rebuilds. Fire claims average around $88,000, the highest-value claim type a Dallas homeowner files, and ALE is the slice of that claim that keeps your family housed while the work happens. Dallas fire restoration averages $29,077, and a full rebuild takes weeks to months, so the ALE limit on your policy decides whether your temporary housing runs out before your home is livable again. The fire damage restoration page covers the full rebuild service, and the fire restoration cost guide breaks down what the work itself costs. However, one ALE rule comes first: ALE pays the extra cost above your normal living expenses, not your whole life — so every receipt and every baseline number matters from day one.
What does additional living expense coverage pay for after a fire in Dallas?
ALE pays the additional cost of living somewhere else while your home is unlivable: a hotel room or a short-term rental, the difference between restaurant meals and your normal grocery spend, laundry service, pet boarding, storage for salvaged belongings, and extra mileage if the temporary home sits farther from work or school. It does not pay your mortgage, your normal grocery bill, or the restaurant meal you would have eaten anyway — the insurer reimburses the increase, not the total. Keep every receipt from the first night, because the adjuster reimburses documented extra spending and disputes anything without paper behind it. The fire damage documentation guide covers the photo and receipt routine that keeps a claim moving. However, one coverage trap applies: ALE only runs while the home is genuinely unlivable, so a habitable room with a closed-off damaged wing can shrink the benefit — get the unlivable determination in writing from the crew or the city inspector.
How much ALE coverage do you actually have?
Most standard homeowners policies set the ALE limit as a percentage of the dwelling limit — commonly around 20% — so a home insured for $300,000 in dwelling coverage would carry roughly $60,000 in ALE, while a $200,000 dwelling limit would carry roughly $40,000. Your declarations page states the exact figure, and it is the first page to pull after a fire. A hotel at $150 a night plus meals burns through $4,500 a month, so a $40,000 limit covers about eight months of modest temporary living — and a family of four in a rental plus restaurant meals burns through it faster. Fire claims average around $88,000, and Dallas fire restoration averages $29,077, so the restoration bill and the living bill compete for the same policy. However, one limit trap applies: ALE is a hard cap, not a monthly allowance — once the limit is spent, the insurer pays nothing more even if the rebuild is unfinished, so track the running total every week.
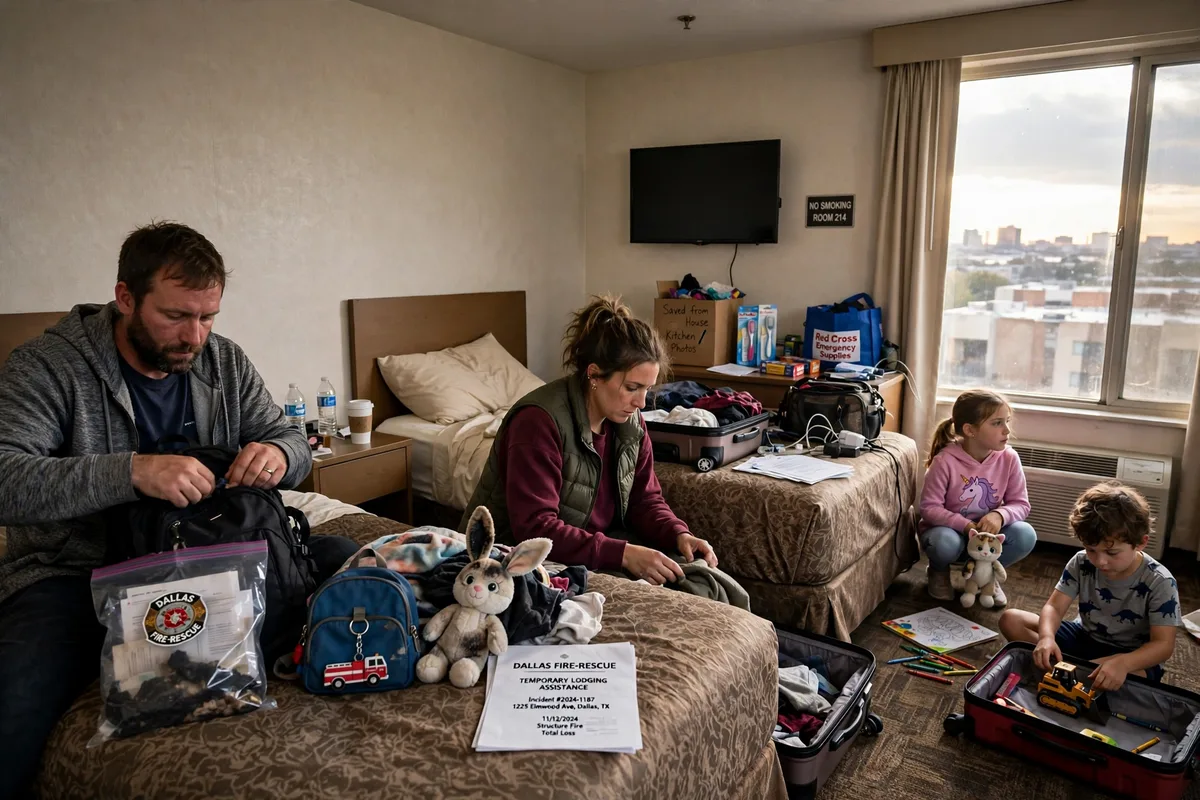
How do you file an ALE claim without losing money?
File the ALE claim the same day as the fire: call your insurer, open the claim number, ask for the ALE limit in writing, and ask whether the carrier advances funds for the first hotel nights. Photograph every damaged room before anything moves, save every receipt in one envelope or one phone folder, and write down your normal monthly grocery, laundry, and transport spending so the adjuster can see the increase clearly. Submit receipts weekly rather than in one pile at the end, because a steady paper trail gets reimbursed faster and disputed less. The fire restoration timeline guide shows how long each phase of the rebuild runs, which sets the ALE clock. However, one filing mistake costs families thousands: throwing away smoke-damaged food or clothing before photographing it, because the adjuster cannot reimburse what was never documented.
| ALE expense | Usually covered | Needs receipts |
|---|---|---|
| Hotel or short-term rent | Yes, full extra cost | Yes, every night |
| Restaurant meals | Extra over groceries | Yes, itemized |
| Laundry service | Yes, extra cost | Yes, keep tickets |
| Pet boarding | Often, check policy | Yes, kennel invoice |
| Storage unit | Yes, salvaged items | Yes, monthly bill |
| Mortgage, normal groceries | No, normal costs | Baseline figures only |
📞 Free Fire Damage Estimate: +1 214-807-4697
What happens when your insurer lowballs your ALE claim?
Insurers lowball ALE claims by questioning whether the home was truly unlivable, by capping the hotel at a nightly rate below Dallas prices, or by calling restaurant meals a normal expense. Push back with the unlivable determination in writing, with Dallas hotel and rental rates printed for the same dates, and with your grocery baseline from bank statements showing the real increase. A public adjuster can take the fight over if the gap is large, and the restoration crew's moisture and soot readings prove the home was unsafe to occupy. Fire claims average around $88,000, so carriers scrutinize the biggest claims hardest, and ALE is the easiest line for them to trim. However, one lowball trap applies: accepting a small ALE settlement in writing can close the ALE portion of the claim, so never sign a release until the rebuild timeline is firm and the total ALE need is known.
How long does ALE last while your Dallas home is being restored?
ALE lasts until your home is livable again or the dollar limit runs out, whichever comes first — and Dallas fire restoration averages $29,077 with a timeline that runs from a few weeks for smoke and soot jobs to several months for a full structural rebuild. The clock starts the night of the fire, not the day the adjuster visits, so the first hotel nights count against the same limit as the last ones. A crew that starts board-up and cleanup the same day shortens the whole timeline, which is why the first call matters more than the first receipt. The timeline guide breaks the rebuild into phases with realistic durations. However, one timing trap applies: ALE does not extend because the contractor is slow, so a written restoration schedule with dates protects both the rebuild and the benefit.
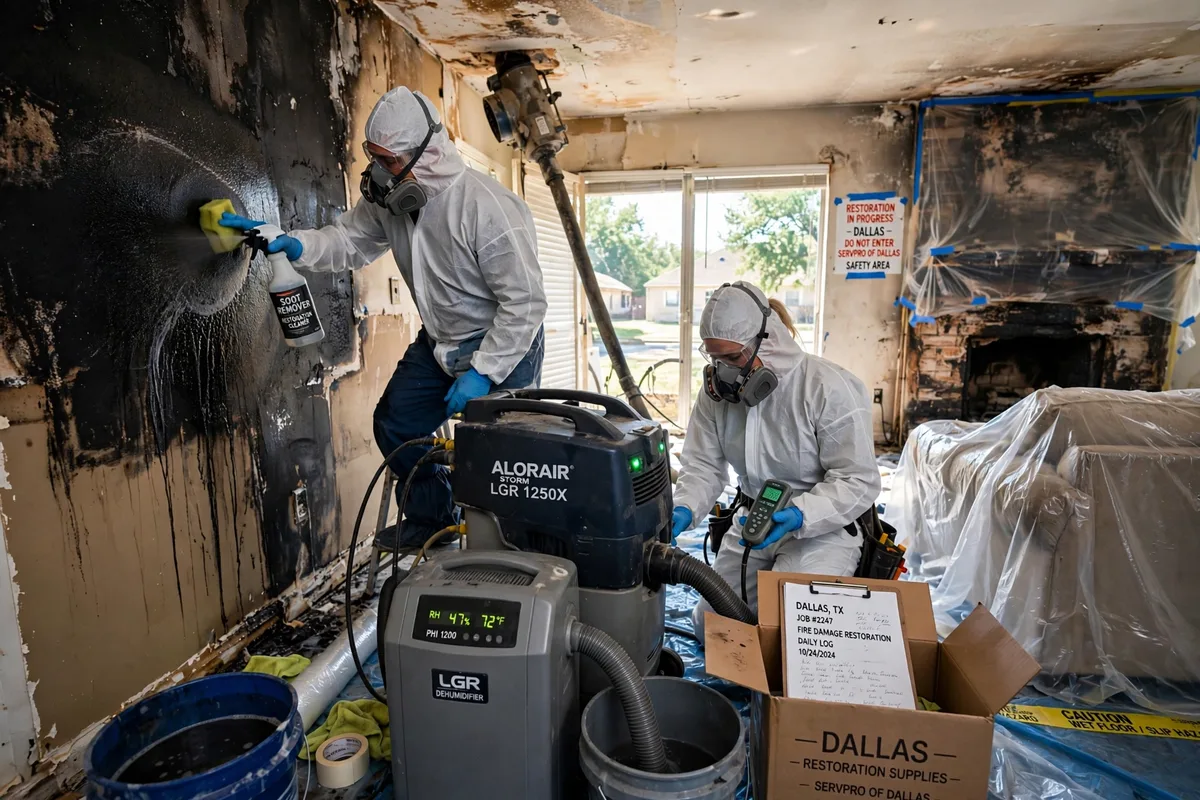
Where do Dallas families actually stay during fire restoration?
Most Dallas families stay in a hotel for the first week, then move to a short-term rental or an extended-stay suite near their neighborhood while the rebuild runs, because a rental with a kitchen cuts the restaurant-meal spend that eats the ALE limit fastest. Families with children pick rentals near the same school zone, and families with pets pick pet-friendly extended stays or boarding plus a rental. The insurer usually lets you choose the accommodation within a reasonable nightly rate, and the adjuster approves the choice faster when you present two or three options with prices. Water damage from firefighting adds a second job — extraction and drying — and mold grows on wet material in 24–48 hours, so the crew handles the water the same night. However, one housing trap applies: booking a luxury suite because the policy seems generous, since the ALE cap is fixed and a luxury first month can leave nothing for month four.
Important Considerations
ALE pays the increase over your normal living costs, not your whole life — keep your baseline grocery, laundry, and transport figures ready from bank statements. Never sign an ALE settlement release before the rebuild timeline is firm, because the benefit ends when the limit or the livability date arrives first. Never throw away smoke-damaged food, clothing, or contents before photographing them, since undocumented losses are rarely reimbursed. Never assume the insurer will advance hotel money — ask for an advance the same day and get the answer in writing. Keep every receipt in one place and submit them weekly, because a steady paper trail is reimbursed faster and disputed less. If the insurer disputes that the home is unlivable, get the determination in writing from the restoration crew or the city inspector. Finally, remember that ALE and the restoration bill draw on the same claim — fire claims average around $88,000 — so a crew that starts the same day and works to a written schedule protects both the rebuild and the living benefit.
📞 Call About Your Fire Claim: +1 214-807-4697
Frequently Asked Questions
What is additional living expense coverage after a fire?
ALE is the part of your homeowners policy that pays the extra cost of living somewhere else while your fire-damaged home is unlivable — hotel or rent, restaurant meals above your normal grocery spend, laundry, pet boarding, and storage.
Does every homeowners policy include ALE coverage?
Most standard policies do, usually set as a percentage of the dwelling limit — commonly around 20%. Your declarations page states the exact figure, so pull it the day of the fire.
How much can ALE pay in a Dallas fire claim?
It depends on your limit — a $300,000 dwelling limit commonly carries around $60,000 in ALE. Fire claims average around $88,000, so the limit decides how long temporary housing lasts.
What ALE expenses does an insurer actually reimburse?
Hotel or rent, the restaurant-meal increase over your normal grocery spend, laundry service, pet boarding, and storage — all with receipts. Mortgage and normal groceries are not covered.
How do I file an ALE claim after a fire?
Call your insurer the same day, get the ALE limit in writing, ask about an advance for the first hotel nights, photograph the damage, and keep every receipt in one folder. Submit receipts weekly.
How long does ALE last during fire restoration?
Until your home is livable again or the dollar limit runs out, whichever comes first. Dallas fire restoration averages $29,077 and runs from weeks for smoke jobs to months for a full rebuild.
Can my insurer refuse ALE if part of my home is still livable?
It can try — ALE only runs while the home is unlivable, so get the determination in writing from the restoration crew or the city inspector before the adjuster decides.
What if my insurer lowballs my ALE claim?
Push back with the written unlivable determination, Dallas hotel and rental rates for the same dates, and your grocery baseline from bank statements. A public adjuster can take the fight over if the gap is large.
Does ALE cover a rental with a kitchen?
Yes — a short-term rental or extended-stay suite is usually covered, and a kitchen cuts the restaurant-meal spend that eats the ALE limit fastest. Present two or three priced options to the adjuster.
Does ALE cover water damage from firefighting?
The water damage itself is part of the fire claim, and the crew extracts and dries it the same night — mold grows on wet material in 24–48 hours. ALE covers your living costs while that work runs.
Why call Water Damage Restoration Dallas after a fire?
Local Dallas crews, 24/7 live answer, around 60-minute arrival, free estimates, and same-day board-up, smoke and soot cleanup, drying, and rebuild — call +1 214-807-4697.
📞 Call Water Damage Restoration Dallas 24/7: +1 214-807-4697
Related Dallas Water Damage Guides
- How Much Does Water Damage Restoration Cost in Dallas? A 2026 Price Guide
- Fire Insurance Claim Mistakes in Dallas: Avoid the Errors That Cost Thousands
- Firefighting Water Damage Restoration in Dallas: Who Pays & How Pros Dry It
- Fire Damage Restoration for Dallas Landlords & Rental Properties: Tenants, Lost Rent & the Claim